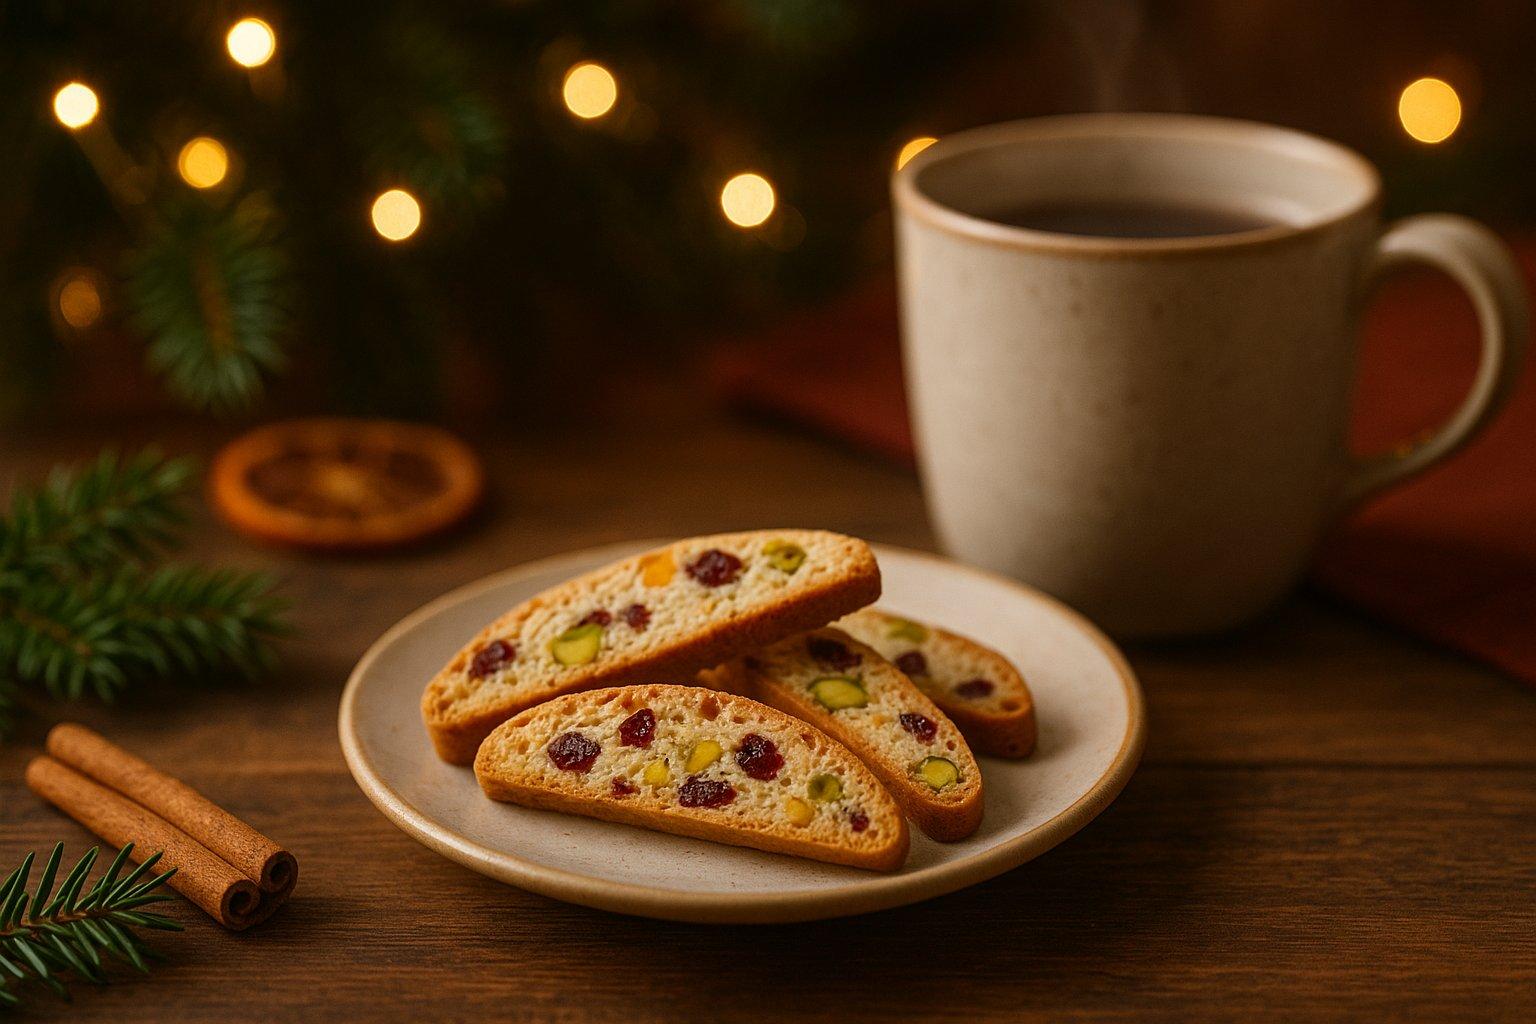
From My Kitchen: Cranberry, Orange & Pistachio Biscotti
Make festive cranberry, orange and pistachio biscotti with this easy homemade recipe. Perfect for Christmas baking, holiday gifts and ...
READ POSTStart with what matters to you.
Make festive cranberry, orange and pistachio biscotti with this easy homemade recipe. Perfect for Christmas baking, holiday gifts and ...
READ POST
Get your home ready for the holidays with five simple spaces to declutter before Christmas. Practical organizing tips for a less stressful December.
READ POST
Buying a home in Calgary involves more than a buyer and seller. Learn what your Realtor, mortgage professional, lawyer, inspector and ...
READ POST
Should you buy your next home before selling your current one? Learn the pros, risks and timing considerations for Calgary homeowners planning a move.
READ POST
Buying a home can feel a little like suddenly being introduced to an entire cast of people you did not know you needed.
Your Realtor. A mortgage broker. A lawyer. A home inspector. Maybe a condo document reviewer. Someone from the insurance company. Possibly an appraiser.
If you have never bought a home before, it can be hard to know who does what, when they get involved, and who you are actually supposed to call when you have a question.
The good news is that you do not need to manage all of these people on your own. Part of my job is helping you understand who needs to be involved, when we need them, and what comes next.
Here are the people you are most likely to encounter during a home purchase in Calgary.
Your Realtor is usually the person beside you through the entire process.
Before we start looking at homes, I want to understand what you are actually trying to accomplish. That includes your budget, preferred areas, lifestyle, must-haves, compromises and timeline.
Once we start the search, I help you evaluate homes, look at comparable sales, understand the market around a property and think through the trade-offs.
When you find the right home, I prepare and negotiate the offer, explain the terms and conditions, keep track of deadlines and coordinate the pieces that need to happen between acceptance and possession.
You will still work with several other professionals along the way, but I help connect the dots between them.
Your mortgage professional helps you understand the financing side of the purchase.
Ideally, this relationship starts before we begin seriously looking at homes.
A mortgage broker or lender can help you understand what you may qualify for, what your payments could look like and what documentation you will need.
Once you have an accepted offer, they will review the actual property and complete the work required for final mortgage approval.
This is why I always encourage buyers to have the financing conversation early. Knowing what you can borrow is helpful. Knowing what you are actually comfortable spending is even more important.
If your offer includes a home inspection condition, you will hire a home inspector after the offer is accepted.
The inspector examines the visible and accessible components of the home and helps you better understand its condition.
They may identify maintenance items, areas of concern or systems that deserve closer attention.
A home inspection is not a guarantee that nothing will ever go wrong with the property. It is another layer of information that helps you make a more informed decision before removing your condition.
Your lawyer becomes especially important as you get closer to possession.
They handle the legal side of transferring the property from the seller to you, work with your lender on the mortgage documents, review the closing information and coordinate the funds required to complete the purchase.
You will usually meet with your lawyer before possession to sign documents and go through the final numbers.
This is also the person you should speak with when you need legal advice about the transaction.
If you are buying a condominium, there is another important layer of due diligence: the condominium documents.
A professional condo document reviewer can help you understand the financial health of the condominium corporation, the reserve fund, bylaws, meeting minutes and other information that may affect you as an owner.
A beautiful unit can still come with concerns at the corporation level, so this review can be just as important as looking at the physical property itself.
Before possession, you will need to arrange insurance for the property.
Your insurance provider will ask questions about the home and the coverage you need. Depending on the property, they may want information about things such as the age of the home, roof, electrical system, plumbing or previous claims.
I recommend starting this conversation before the last minute. If an insurance company has questions about the property, it is much easier to deal with them when you still have time.
Not every buyer will personally arrange an appraisal, but one may become part of the financing process.
A lender may require an appraisal to help confirm that the property supports the value being financed.
If one is required, it is generally part of the lender’s process rather than something you need to organize independently.
It is another reason final mortgage approval depends on more than your personal finances. The lender is also looking at the property you are buying.
You are actually the most important person in the transaction.
There will be a lot of professional opinions, numbers, documents and deadlines along the way, but ultimately the decisions are yours.
My job is not to push you toward a particular house or make those decisions for you. It is to make sure you have the information you need, understand your options and know who to turn to when something falls outside my area of expertise.
You should feel comfortable asking questions at every stage.
One of the reasons buying a home can feel overwhelming is that there are a lot of moving parts, especially once an offer is accepted.
But you are not expected to suddenly become an expert in mortgages, contracts, inspections, insurance and property law.
You have a team for that.
My role is to help keep the process organized, make sure you know what needs to happen next and help you bring in the right professionals when you need them.
Your process, your timeline. You just need to know what decision is in front of you next, not memorize the entire transaction before we begin.
If you already own a home and you’re thinking about moving, one of the first questions that usually comes up is also one of the hardest to answer:
Do I buy first, or sell first?
There isn’t one right answer for everyone. The better choice depends on your finances, the current market, how specific your next-home search is, how much flexibility you have with timing, and how comfortable you are carrying some uncertainty.
What matters most is understanding the trade-offs before you make the decision.
Buying first can make a lot of sense if finding the right next home is going to take time.
Maybe you are looking in a very specific neighbourhood. Maybe you need a certain layout, school district, lot, garage or number of bedrooms. If the right properties do not come up very often, buying first gives you the freedom to wait for something that genuinely works rather than feeling pressured to choose whatever is available because your current home has already sold.
It can also make the transition between homes feel easier. You know where you are going, you can plan possession dates, and you are not trying to find a new home while the clock is ticking on your sale.
The challenge, of course, is financial.
Buying first may mean carrying two properties for a period of time, arranging bridge financing, or making an offer that is conditional on the sale of your existing home. Whether any of those options are realistic depends on your financial situation and the lender involved.
That is why I want my clients to speak with their mortgage professional before we decide on this route. We need to know what is possible before we start writing offers.
Selling first gives you certainty.
Once your home is sold, you know exactly how much equity you are working with and you are no longer guessing about what your current home may sell for. That can make budgeting for the next purchase much easier.
It also means you are not carrying two homes at once.
For some buyers, that financial peace of mind is worth a lot.
The trade-off is that once your home sells, there is now a timeline attached to your search. If possession is approaching and we have not found the right property yet, you may need to make temporary housing arrangements or be more flexible about what you buy.
That is not necessarily a problem, but it is something we should plan for before putting your home on the market.
The market can influence which strategy makes more sense.
If homes like yours are selling quickly but the type of property you want to buy is harder to find, buying first may be worth considering.
If your current home could take longer to sell, selling first may reduce the risk of owning two properties for longer than you intended.
And sometimes the market is balanced enough that we can coordinate both sides fairly closely.
This is one of the reasons I do not like giving buyers and sellers a blanket answer to this question. The right strategy can change depending on the market, the property and your personal situation.
This is a big one.
If you are moving because you simply want a little more space and you are open to several communities, layouts and styles of home, you may have plenty of options once your current property sells.
But if your wish list is very specific, the search may take longer.
Maybe you need a triple garage. Maybe you want to stay within one school boundary. Maybe you need a main-floor office, a certain commute or a particular lot orientation.
The more specific the search, the more important it becomes to think carefully about selling first and putting yourself on a deadline.
This is one of the most useful questions to ask yourself.
If your home sells and the right next property has not come along yet, would you be comfortable renting temporarily? Staying with family? Putting some belongings into storage?
For some people, that is completely manageable.
For others, the idea of moving twice makes selling first feel far less appealing.
Neither answer is wrong. It is simply part of figuring out which option fits you best.
Buying and selling do not always have to happen on exactly the same day.
Sometimes we can negotiate possession dates that give you a little extra breathing room between the two transactions. A longer possession on your sale or a carefully chosen possession date on your purchase can make the transition much smoother.
There are limits to how much timing we can control, especially when other buyers and sellers are involved, but possession dates are an important part of the strategy.
In some situations, a buyer may write an offer that is conditional on selling their existing home.
That can reduce some of the financial risk of buying first, but it also makes the offer more complicated for the seller. In a competitive situation, a seller may prefer an offer that does not depend on another property selling.
Whether this type of condition makes sense depends on the property, the market and the amount of competition.
It is an option, not an automatic solution.
Before making the decision, I usually want to understand three things:
What is your current home likely to sell for and how long could that take?
How difficult is it likely to be to find the home you want to buy?
And financially, how much flexibility do you realistically have between the two transactions?
Once we know those answers, the decision becomes much clearer.
For some clients, selling first gives them the certainty they need. For others, finding the right next home is the bigger priority, so buying first makes more sense.
The goal is not to follow a rule. It is to build a plan around your situation.
If you are thinking about selling your current home and buying another one in Calgary, we can look at both sides of the move before you commit to either. That way, you know what the options are, what the risks are, and what strategy gives you the most flexibility.
When buyers start thinking about what they can afford, most of the attention naturally goes to the purchase price and the mortgage payment. Those are obviously important, but they are not the only costs that come with buying a home.
There are several expenses that can come up between writing an offer and getting the keys, and a few more that show up shortly after possession. Knowing about them ahead of time makes the process a lot less stressful and helps you build a more realistic budget from the beginning.
Here are some of the costs Calgary buyers should be prepared for.
Once your offer is accepted, you will usually be required to provide a deposit within the timeframe written into the contract.
The deposit forms part of your purchase price, so it is not an extra cost on top of what you are paying for the home. However, you do need to have those funds available when the deposit is due.
The amount can vary depending on the property, the price and the situation, so this is something we will talk about when we are preparing your offer.
If your offer includes a home inspection condition, the inspection is paid for by you as the buyer.
A home inspection gives you an opportunity to learn more about the condition of the property before you remove your condition and move forward with the purchase. It can help identify visible issues, maintenance concerns and systems that may need attention.
Inspection fees vary depending on the size and type of home, and there may be additional costs if you choose to have specialized inspections completed.
If you are buying a condominium, you may also want to have the condominium documents professionally reviewed.
A condo document reviewer can help you understand the financial position of the condominium corporation, reserve fund information, bylaws, meeting minutes and other details that could affect your ownership.
This is an additional cost, but it can provide valuable information before you make the purchase firm.
You will need a real estate lawyer to complete the legal side of your purchase.
Your lawyer handles things such as reviewing the purchase contract, transferring title, dealing with mortgage documents, coordinating funds and ensuring the property is legally transferred to you.
Legal costs can vary depending on the transaction, the lender and the complexity of the purchase, so it is a good idea to ask your lawyer for an estimate ahead of time.
There are also costs associated with registering the transfer of the property and, if applicable, registering your mortgage.
These are normally handled through your lawyer and included as part of your closing costs.
They are easy to overlook because they do not show up during the home search, but they are part of the money you will need available before possession.
Property taxes are often adjusted between the buyer and seller on closing.
Depending on when the seller has paid their taxes and when possession takes place, you may either receive a credit or be responsible for reimbursing the seller for a portion of the taxes they have already paid.
Your lawyer calculates this adjustment as part of the closing process.
Your lender will typically require proof of home insurance before mortgage funds are released.
That means insurance is something you should arrange before possession, not after you move in.
The cost depends on the property and your coverage, and some features of a home can affect insurance availability or pricing. Starting the conversation with an insurance provider early gives you time to deal with any questions that come up.
Moving costs can vary widely depending on how much you are moving, how far you are going and whether you hire professional movers.
Even if you are doing the move yourself, there may still be costs for boxes, supplies, truck rentals, storage or cleaning.
It is worth including some room in your budget for the move itself rather than assuming possession day will be the end of the expenses.
When you take possession, you will need to arrange utilities and services for the property.
Depending on the home, this may include electricity, natural gas, water, internet, security systems or other services.
Some providers may require setup fees, deposits or account transfers.
This is the category that is easiest to underestimate.
Even a home that is in excellent condition often comes with a list of things buyers want to do shortly after moving in. Maybe you need blinds for a room that did not have them, a lawn mower, shelving, paint, furniture or a few small repairs.
None of those things may be urgent individually, but they can add up quickly.
I always encourage buyers to leave some room in their budget after possession instead of putting every available dollar into the purchase itself.
The cost of buying a home is not just the purchase price.
When we talk about your budget, I want you to understand the full picture so you are not surprised by expenses as you move through the process.
That does not mean you need to have every cost perfectly calculated before you begin. It means knowing what is likely to come up, asking questions early and making sure you have some breathing room.
Buying a home should feel exciting, not like a series of unexpected bills.
If you are thinking about buying a home in Calgary, we can talk through your budget, your timeline and what expenses you should plan for before you start seriously looking.
Buying a home can be exciting, overwhelming and occasionally a little emotional, sometimes all in the same afternoon. There are a lot of decisions to make, and most buyers are trying to process those decisions while also thinking about mortgages, neighbourhoods, inspections, possession dates and whether that kitchen they loved is distracting them from something more important.
You do not need to know everything before you start. That is part of why you have professionals around you. But there are a few common mistakes that can make the process more stressful, more expensive or simply harder than it needs to be.
Here are eight I would try to avoid.
Before we start seriously looking at homes, I want you to have a clear idea of what you can comfortably spend.
A mortgage pre-approval gives us a realistic starting point and helps narrow the search to homes that actually fit your financial picture. Just as importantly, there can be a big difference between the maximum amount a lender may approve and the monthly payment you actually feel comfortable carrying.
Your budget also needs room for the costs that come with buying and owning a home, not just the mortgage payment itself.
The goal is not to shop at the very top of what you qualify for. It is to understand your options before you fall in love with a home that does not fit them.
Some homes photograph beautifully. Others do not.
The same thing happens when you walk through the door. A beautifully styled home can make it very easy to overlook things that matter, while dated paint, furniture or finishes can distract you from a home that actually has a great layout, location or lot.
I encourage buyers to separate the things that are easy to change from the things that are not.
Paint can change. Flooring can change. Light fixtures can change.
Location, lot orientation, room proportions, natural light and the basic layout of the home are much harder to change.
You can absolutely love how a home feels. Just make sure the feeling is not doing all of the decision-making.
A home inspection gives you an opportunity to learn more about the condition of the property before you move forward with the purchase.
That does not mean an inspector will find every possible problem or predict everything that could happen in the future. What they can do is help identify visible concerns, maintenance issues and systems that may require attention.
If something significant comes up, we can look at the information together and talk through your options based on the contract and the circumstances.
The important part is making an informed decision rather than assuming that because a home looks good, everything behind the walls is perfect too.
A purchase contract is not just paperwork we need to get through so we can submit an offer.
Price matters, but so do conditions, deposits, inclusions, possession dates, deadlines and the other terms that form part of the agreement.
Before an offer is submitted, I want my buyers to understand what they are agreeing to and what happens next. If something is unclear, that is the time to stop and ask questions.
You should never feel like you need to sign quickly simply because there are a lot of pages in front of you.
The asking price is a marketing decision. It is not automatically the market value of the property.
When we are considering an offer, I look at the home in the context of the current market. What have comparable properties sold for? How does this home compare in condition, location, size and features? How long has it been on the market? Is there competing interest?
Sometimes a home is priced aggressively to generate activity. Sometimes it is priced optimistically. Sometimes it is very close to where the market supports it.
The offer strategy should be based on the property and the market around it, not simply on a percentage above or below the asking price.
You are not only buying the home. You are also choosing the environment around it.
Think about the things you will interact with every day. Your commute. Schools. Parks. Groceries. Transit. Traffic. Walkability. Nearby development. How long it takes to get to the places that are part of your actual life.
I often tell buyers to visit an area more than once if they are not familiar with it. Drive through during a weekday. Go back in the evening. Look at the surrounding streets, not just the block the house is on.
A home can check every box and still be the wrong fit if the location does not work for the way you live.
Property insurance is one of those details that can easily get pushed to the bottom of the list when you are focused on financing, inspections and possession.
Do not leave it until the night before you get the keys.
Insurance providers may ask questions about the property, and certain features or previous issues can affect coverage or pricing. Giving yourself some time means you can ask questions, compare options and deal with any surprises before possession is right around the corner.
It is a small piece of the buying process, but it is much easier when it is handled early.
Negotiation is not simply about getting the seller to accept the lowest possible number.
Price is one part of an offer. Conditions, possession date, deposits and other terms can also matter to a seller. The right strategy depends on the home, the competition, the seller's circumstances and what matters most to you as the buyer.
Sometimes a lower offer makes sense. Sometimes it does not.
My job is to help you understand the information we have, talk through the trade-offs and build an offer that gives you the best chance of getting the home without losing sight of your own limits.
There will always be decisions to make when you buy a home. The goal is not to eliminate every bit of uncertainty. It is to make sure you have enough information to make those decisions confidently.
Your process, your timeline. We can take the time to understand the financing, look closely at the homes, talk through the trade-offs and make decisions that feel right for you.
If you are thinking about buying a home in Calgary and want to know what your first step should be, I would be happy to talk through where you are in the process and what comes next.
Getting an accepted offer is exciting, but there is still quite a bit that happens before possession day. This stage is about working through conditions, confirming financing, preparing for closing, and making sure everything is ready for the transfer of ownership.
If your offer includes conditions, this is the time to satisfy them before the agreed deadline. For many buyers, that means finalizing financing, completing the home inspection, reviewing condominium documents where applicable, or addressing any other conditions written into the contract.
Once all conditions are satisfied or waived, the deal becomes firm.
Even if you were pre approved, your lender still needs to approve the actual property and transaction. They may ask for the purchase contract, an appraisal, updated financial documents, or additional information.
This is why I caution buyers against making major financial changes before possession. New debt, a vehicle purchase, a job change, or another large financial commitment can affect financing at exactly the wrong time.
Once the deal is firm, your lawyer becomes more involved. They prepare the transfer of ownership, calculate the funds needed for closing, review the legal documents, and make sure everything is ready for possession day.
This is also when buyers should have home insurance arranged and be prepared for legal fees, adjustments, and the remaining funds required to close.
Shortly before possession, we usually return to the property for a final walkthrough.
This is not another inspection and it is not an opportunity to reopen negotiations. It is simply a chance to confirm that the property is in substantially the same condition as when you agreed to buy it and that the items included in the contract are still there.
The purchase contract is typically written for completion by noon on possession day. Your lawyer handles the final transfer of funds and legal documents, and once everything is confirmed, the keys can be released.
In practice, delays are not uncommon, and one side may need to ask the other lawyer for a short extension while funds or paperwork are being completed. Because of that, I always recommend leaving some breathing room in your moving schedule rather than planning around having keys first thing in the morning.
There is still a lot of coordination happening after the offer is signed. I am tracking condition deadlines, communicating with the other side, helping with inspection questions, making sure documents are completed properly, and helping you understand what happens next.
For most buyers, this is not a process they go through often. My job is to make sure you always know where things stand and what needs to happen next.
This buyer series is meant to break the process down into practical pieces, and I’ll continue adding to it over time.
If you are planning to buy and want a more complete overview, I also have a Buyer’s Guide that walks through the process from preparing to buy all the way to possession.
If you would like a copy, send me a message and I’ll get one to you.
Erika Dix, Realtor
The Real Estate District
You have an accepted offer, your inspection is booked, and then you receive a report that feels like it is 80 pages long.
For a lot of buyers, this is where the stress starts. But a home inspection is not about finding a perfect house. It is about understanding the house you’re buying and identifying anything that may affect your decision before you move forward.
A home inspection gives you a closer look at the visible condition of the property. The inspector may review things like the roof, exterior, grading, foundation, attic, insulation, plumbing, electrical, heating, cooling, windows, doors and visible structural components.
The goal is to identify concerns, maintenance items and anything that may require further investigation.
A long report does not automatically mean the house is a bad one. Inspectors document everything, from major concerns to minor maintenance items. The important part is sorting out what matters now, what may matter later and what is simply part of normal home owner maintenance.
By the time my buyers reach the inspection, many of the obvious concerns have already been discussed.
While they are deciding whether they can picture themselves living in the home, I am usually focused on the structural and mechanical components, things like the furnace, hot water tank, plumbing, windows, roof, grading and any visible moisture concerns.
Because I have worked in new home construction and grew up alongside a father who built our family homes from the ground up, I have a strong understanding of how homes are put together.
I am not a home inspector, but I can often identify things worth discussing before we write an offer. That means known items such as an older furnace or Poly B plumbing can be considered in the price and terms from the beginning, rather than becoming a surprise later.
This is where working with the right buyer’s agent matters. A good agent should help you identify potential concerns early, understand how they may affect value, and use that information when helping you structure your offer.
A home inspection is visual and non invasive. An inspector can only identify what is visible and present at the time of the inspection. They cannot see behind finished walls, under flooring or inside every system, and they cannot predict future failures.
A furnace may be working perfectly on inspection day and fail months later. A roof may show no active leak and develop one in the future. An inspection is not a guarantee against future repairs.
Sometimes the inspector will recommend that another professional take a closer look, such as an electrician, plumber, roofer, HVAC technician or structural engineer. The inspection is often the starting point for asking better questions.
This depends on what was found and how significant it is.
Sometimes the buyer is comfortable moving forward. Sometimes more information is needed. In other cases, something substantial may change how the buyer feels about the property.
What is important to understand is that the inspection condition is not there to automatically reopen negotiations, and it is not a “honey do” list for the seller to complete before possession.
The purpose is to help the buyer decide whether they are still comfortable moving forward based on what they now know.
If a major concern is discovered, there may be a reason for further discussion. That is very different from going back to the seller with every small maintenance item or cosmetic issue.
Every home requires maintenance. The real value of the inspection is helping you understand what you are taking on as the future homeowner.
Instead of asking, “What can I get the seller to fix?” I encourage buyers to ask, “Now that I know more about this home, am I still comfortable moving forward?”
By the time we reach the inspection, I already know what you loved about the house, what compromises you were willing to make and what mattered when we wrote the offer. That context helps us decide how much weight to give anything that comes up.
An inspection should not leave you more afraid of the property. It should leave you more informed.
If you have been following the Calgary Home Buyer Series, Parts 1 and 2 focused on choosing the right Realtor and understanding what goes into an offer. This is where those pieces start to come together.
If you are thinking about buying and want to understand how inspections fit into the process, send me a message. I am always happy to walk you through it.
Erika Dix, Realtor
The Real Estate District
You found the house. Now comes the part where a lot of buyers assume the conversation is simply:
“What should we offer?”
Price matters, of course. But a purchase contract includes much more than the number at the top, and sometimes the terms surrounding the price can be just as important.
A good offer is not just about being competitive. It is about protecting you while also putting together terms the seller can realistically work with.
The obvious place to start is price. Before writing an offer, I usually want to look at more than the list price. We may review comparable sales, current competition, how long the property has been listed, previous price changes and what we know about the current market.
The goal is not simply to decide how much you can offer. It is to decide what the property is worth to you and how that number fits into the overall strategy of the offer.
The deposit forms part of the purchase contract and shows the seller that you are serious about completing the transaction. It is not an additional cost on top of the purchase price. If the sale completes, the deposit is credited toward the purchase price.
Remember, the amount of the deposit, when it needs to be delivered and how it is held all matter. Those details need to be clearly set out in the contract.
Most buyers are familiar with financing and home inspection conditions, but there can be others depending on the property.
A condominium purchase may include a condition for reviewing condominium documents. A rural property may require additional inspections or testing. A buyer may also need a condition related to the sale of their current home.
Conditions need clear deadlines, and buyers should understand exactly what needs to happen before they remove them. Once conditions are waived, the contract generally becomes firm and binding.
There are situations where buyers consider writing an offer without conditions, particularly in a competitive market. That can make an offer more attractive to a seller, but it also removes important protections. It is a decision that should be made with a clear understanding of the risk, not simply because someone says, “That’s what you have to do to win.”
Possession date is another piece buyers sometimes underestimate.
You may want the house as quickly as possible, while the seller may need additional time to move or complete their own purchase. Sometimes flexibility on possession can make an offer more appealing without increasing the purchase price at all. That is why I always want to understand not only what matters to my buyer, but what we know about the seller’s needs as well.
This is one of those details that feels small until it causes a problem.
Attached items will generally remain with the property unless the contract says otherwise. Unattached items generally do not, unless they are specifically included. That means we may need to talk about things such as appliances, window coverings, garage shelving, televisions and mounts, outdoor structures or anything else you expect to be there when you take possession.
If something matters to you, it should be clear in the contract.
Offers contain important deadlines.
There is a deadline for the seller to accept the offer, deadlines for satisfying conditions, deposit timing and, eventually, possession.
These are not filler dates. They affect how the transaction unfolds, and they need to give you enough time to properly complete whatever due diligence you have agreed to do.
This is one of the most important things for buyers to understand.
Imagine a seller receives two offers:
One has a slightly higher price but several conditions, a difficult possession date and a smaller deposit.
The other is slightly lower but has terms that fit the seller’s situation much better.
The seller may prefer the second one.
That does not mean you should automatically remove conditions or give the seller everything they want. It means we look at the whole offer.
Price is part of the strategy. So are the terms.
Writing an offer is not about filling in blanks on a form. My job is to help you understand what you are agreeing to, identify the areas we need to think through and build an offer that reflects both the property and your circumstances. Sometimes that means being aggressive or it may mean protecting yourself with conditions. Sometimes it means changing the possession date instead of changing the price, and, believe it or not, sometimes my advice is that the best offer is the one we do not write.
The goal is not simply to get an accepted offer.
It is to get you into the right property on terms you understand and are comfortable with.
If you read Part 1 of the Calgary Home Buyer Series, you already know how important it is to have someone representing your interests. Writing the offer is where that really starts to matter.
If you’re thinking about buying and have questions about how an offer is actually put together, send me a message. I’m always happy to talk through the process before we’re in the middle of it.
Erika Dix, REALTOR®
The Real Estate District


When buyers first start looking for a home, it can feel logical to keep their options open. You might call the listing agent on one property, another Realtor on the next, and someone else when a friend sends you a listing. The thinking is that more Realtors means more help.
In reality, it usually works the opposite way.
Buying a home is not just about bedrooms, bathrooms and price.
The longer I work with a buyer, the more I learn about what really matters to them. Sometimes I can identify those preferences before they can even put them into words themselves. A buyer may say they liked a home, but after talking it through, we realize they disliked the lack of natural light, the busy street, the layout or the amount of work it needed. That helps me ask better questions and guide the search more effectively.
It is easy to look at a new listing and think, “This looks great,” without stopping to ask, “Didn’t I dislike this exact feature in the last house?” That kind of pattern recognition only happens when one Realtor is involved consistently.
If you are calling a different agent every time, each one is starting from scratch.
Agents value loyalty.
When I know someone has chosen me as their Realtor, I am invested in their search. I am watching listings, researching properties, looking at comparable sales, booking showings and thinking ahead to what may matter when it is time to write an offer.
If I know a buyer is also working with several other agents and simply calling whoever is available, it becomes a very different relationship.
The clients who commit to working with me get my commitment in return.
Opening the door is one of the smallest parts of my job.
When you are my represented buyer, I can help you evaluate value, identify concerns, discuss strategy, structure an offer, explain conditions and negotiate on your behalf.
That is very different from contacting the listing agent directly because the listing agent represents the seller.
If you choose to proceed without your own representation, that agent is not there to advise you on what is best for you or advocate for your position. Their obligation is to the seller.
One of the biggest benefits of having your own Realtor as a buyer is that, in many Alberta residential transactions, the seller pays the compensation offered to the buyer’s brokerage as part of the sale. In other words, buyers will often have their own representation without writing a separate cheque to their Realtor at closing.
That said, compensation is negotiable and it is not identical in every transaction. Your buyer representation agreement should clearly explain how your brokerage is being paid and whether there could ever be a difference between the compensation being offered by the seller and the fee agreed to in your representation agreement. RECA’s buyer representation agreement specifically allows the buyer’s brokerage to ask the seller or seller’s brokerage to pay its fee, while also addressing what happens if there is a shortfall.
There is also a common misconception that if you choose not to have your own Realtor, the compensation that may have been offered to a buyer’s brokerage automatically becomes a discount to you.
It does not.
The listing agent represents the seller and is there to protect the seller’s interests. They are not there to advocate for that compensation to be redirected to you as a buyer. Any change to the purchase price, compensation, or other terms would still need to be negotiated and agreed to as part of the transaction.
This is another reason I think buyers should understand the difference between being represented and simply dealing directly with the listing agent.
There is nothing wrong with interviewing more than one Realtor. You should! Ask how they work, how they communicate and what they actually do for buyers beyond sending listings and opening doors. Once you find the right person, give that relationship a chance to work.
You do not need five Realtors competing for your business. You need one Realtor who understands what you are looking for, knows how to guide you through the process and is genuinely invested in helping you make a good decision.
Thinking about buying in Calgary and not sure where to start? I’m always happy to walk you through the process before you ever step inside a showing.
Erika Dix, REALTOR®
The Real Estate District
I can usually tell within the first few minutes. A buyer walks through the front door, pauses for just a second longer than they have at the other homes we've seen, and I know something has changed.
Maybe it's the way the morning light pours through the kitchen windows. Maybe it's the backyard they've already imagined hosting summer barbecues in, or the cozy reading nook tucked beside the fireplace. Whatever it is, they're no longer just touring a house. They're beginning to picture a life. And honestly, I love that part of the process.
Buying a home should be emotional. Home is where birthdays are celebrated, where kids grow up, where friends gather around the kitchen island talking long after dinner is over. It makes sense that we'd choose a home with our hearts as much as our heads.
The challenge is that emotions have a way of making everything else a little quieter.
Suddenly the layout that didn't quite work doesn't seem like such a big deal. The busy road out front becomes easy to ignore. The aging furnace or the lack of storage somehow feels less important because you've already started imagining where the Christmas tree will go.
That's why I believe one of the most valuable things I bring to my buyers isn't simply opening doors.
It's perspective.
While you're imagining where your furniture will go, I'm quietly paying attention to how the home functions. I'm thinking about resale, maintenance, the flow of the floor plan, and whether the things you're compromising on today might become the things that frustrate you a few years from now.
That doesn't mean I'm trying to talk anyone out of falling in love with a home. Quite the opposite. I want my clients to find the home they're excited to come back to every single day. I just want that excitement to be built on a foundation that's going to serve them long after the excitement of possession day has passed.
I've also learned that sometimes the opposite happens.
Buyers walk into a home and immediately dismiss it because the walls are painted a colour they would never choose or the light fixtures haven't been updated since the early 2000s. Meanwhile, the layout is fantastic, the neighbourhood is exactly what they've been hoping for, and the things they dislike could be changed over a weekend.
It's funny how easily we can be distracted by what's temporary and overlook what isn't.
The homes people are happiest in years later usually aren't the ones that checked every single box the day they bought them. They're the ones that fit the way they actually live.
Over the years, I've realized that buying a home isn't about finding perfection. It's about finding the place that makes sense for your life, your goals, and the season you're in.
The excitement should absolutely be there. I want my clients to walk into a home and feel something. I also want them to sleep well the night after they write an offer, knowing they made a decision with both their heart and their head.
The best home isn't always the one that gives you butterflies. It's the one you're still grateful you chose five years later.
Summer is one of the busiest times of year for vacations and for real estate.
Every year, I hear the same question:
"What happens if we get an offer while we're away?"
The good news is that selling your home while you're on vacation is not only possible, it's often easier than people expect. In fact, some sellers actually prefer being away during the busiest part of the process.
A little planning goes a long way.
Before you leave, we'll make sure your home is ready for showings, discuss how you'd like offers handled, and make a plan for staying in touch while you're away.
We'll also talk about things like:
Your preferred communication method
Time zone differences
How quickly you'd like to review offers
Any decisions you'd like to make ahead of time
When everyone knows the plan, there's very little that can't be handled remotely.
In many ways, being away can actually make showings easier.
You don't have to rush home to tidy up after work, load the kids into the car, or find somewhere to spend an hour while buyers walk through.
Your home stays ready for showings, and buyers can view it with fewer scheduling obstacles.
Less disruption for you often means more flexibility for buyers.
Today's real estate process is designed to work wherever you are.
Offers, amendments, disclosures, and other documents can all be reviewed and signed electronically. Whether you're at a lake in British Columbia or on a beach halfway around the world, we can keep everything moving without interrupting your vacation.
Before you leave, it's worth taking a few extra steps to give yourself peace of mind.
Pause mail and package deliveries, or ask a neighbour to collect them (depending how long your vacationing for)
Put interior lights on timers.
Avoid announcing your travel dates on social media.
Leave a spare key with someone you trust in case something unexpected comes up.
Let your Realtor know how to reach you in an emergency.
These small details help your home stay looking lived in while you're away.
It might sound surprising, but many of my clients tell me they enjoyed the process more because they weren't living through every showing notification. Instead of wondering how each showing went or feeling tempted to straighten another pillow before the next one, they were able to relax and enjoy their vacation while I handled things back home.
Sometimes a little distance makes the process feel a lot less stressful.
Selling your home doesn't have to mean putting your summer plans on hold. With a little preparation, clear communication, and the right strategy, your sale can continue smoothly while you're away making memories.
Around the Kitchen Island: Life doesn't stop because your home is on the market. My goal is to make sure your real estate plans fit around your life, not the other way around.
Few words cause as much concern during a home inspection as Poly-B plumbing.
I've seen buyers immediately assume a home is "bad," and I've seen sellers worry their home has suddenly lost all of its value. The truth usually falls somewhere in the middle.
Like many things in real estate, it's important to understand the facts before jumping to conclusions.
Poly-B, short for polybutylene, is a grey plastic plumbing pipe that was commonly installed in Canadian homes from the late 1970s through much of the 1980s and into the 1990s. At the time, it was considered an affordable, flexible alternative to copper and was installed in hundreds of thousands of homes across Canada, including many right here in Calgary.
If your home was built during that period, there's a reasonable chance it contains Poly-B plumbing.
Over time, some Poly-B systems have developed leaks or failures. Research suggests that age, water chemistry, installation practices, and the fittings used all play a role. Not every Poly-B system fails, but enough have experienced issues that it has become something buyers, inspectors and insurance companies pay close attention to.
That doesn't mean every home with Poly-B is destined for problems.
In fact, many Calgary homeowners have lived in homes with Poly-B for decades without ever experiencing a leak. Others choose to replace it proactively during renovations or before selling simply for peace of mind.
For many homeowners, insurance has become a bigger concern than the plumbing itself.
Some insurers may charge higher premiums, require additional documentation, or ask that the plumbing be replaced before offering or renewing coverage. Others continue to insure homes with Poly-B, particularly if there have been no previous issues. Policies vary significantly between insurance companies, which is why it's always worth checking before buying a home.
Not necessarily.
A home should always be evaluated as a whole. Its location, condition, maintenance history, price, and overall value all matter. Poly-B is simply one factor in that equation.
If a home has Poly-B, I recommend:
Having a professional home inspection.
Confirming insurance options before removing conditions.
Obtaining a replacement estimate so you understand the potential future cost.
Factoring that information into your buying decision if appropriate.
For many buyers, it's a manageable consideration rather than a deal breaker.
One of the things I remind clients is that every generation of homes has something buyers ask questions about.
Older homes may have aluminum wiring or asbestos-containing materials. Newer homes may have different concerns altogether. Poly-B simply happens to be one of the common discussion points for homes built during a particular era.
Real estate isn't about finding the perfect house. It's about understanding the home you're buying, knowing what to expect, and making informed decisions with your eyes wide open.
Knowledge is almost always less intimidating than uncertainty, and that's exactly why conversations like this matter.